SEPA Direct Debit: Everything You Need To Know

Permitted by SEPA regulations in all countries within the same zone, SEPA Direct Debits offer the advantage of enabling the collection of regular or one-off amounts directly from your clients’ accounts through the signing of a valid mandate. This payment method accelerates the collection of direct debits, simplifies administrative processes, reduces the risk of error, and improves visibility over cash-flow.

In this article, our experts will explain what a SEPA direct debit is, its advantages, in which cases it might be useful to offer them to your clients and how to practically implement this in your organization.

What is a SEPA Direct Debit?

The SEPA Direct Debit (SDD) allows the creditor to perform one-off or recurring euro debit operations on their clients’ accounts in all countries within the SEPA zone.

These operations are permitted based on a direct debit mandate signed by the debtor, simply by indicating the unique mandate reference number (RUM). The international bank account number (IBAN) and bank identifier code (BIC) can also optionally be provided.

The SEPA Direct Debit exempts the creditor from sending a payment title for each settlement or recurring operation deadline since it has explicit consent to directly debit the due amount from the bank account.

SEPA Direct Debit

Types of SEPA Direct Debits

There are two types of SEPA direct debits. Both are intended to replace “classic” domestic domiciliations as we have known them before 2010.

SEPA Core Direct Debit

The SEPA Core Direct Debit is suitable for all customers, in both B2C and B2B.

SEPA Business To Business Direct Debit

The SEPA Business To Business Direct Debit is exclusively intended for payments between companies, organizations and professionals, under specific conditions.

Countries in the SEPA Zone where Direct Debit are possible

SEPA Direct Debit operations are possible throughout the SEPA zone (link to the blog article), which currently includes 36 countries and benefits from broad geographic coverage.

This includes:

  • All European Union member countries: Germany, Austria, Belgium, Bulgaria, Croatia, Cyprus, Denmark, Spain, Estonia, Finland, France, Greece, Hungary, Ireland, Italy, Latvia, Lithuania, Luxembourg, Malta, Netherlands, Poland, Portugal, Romania, Slovakia, Slovenia, Sweden, Czech Republic
  • Some countries from the European Economic Area (EEA) not (or no longer) part of the EU: Iceland, Liechtenstein, Norway
  • Other countries outside the EEA: Andorra, Monaco, United Kingdom, San Marino, Switzerland, Vatican.

Advantages of SEPA Direct Debits

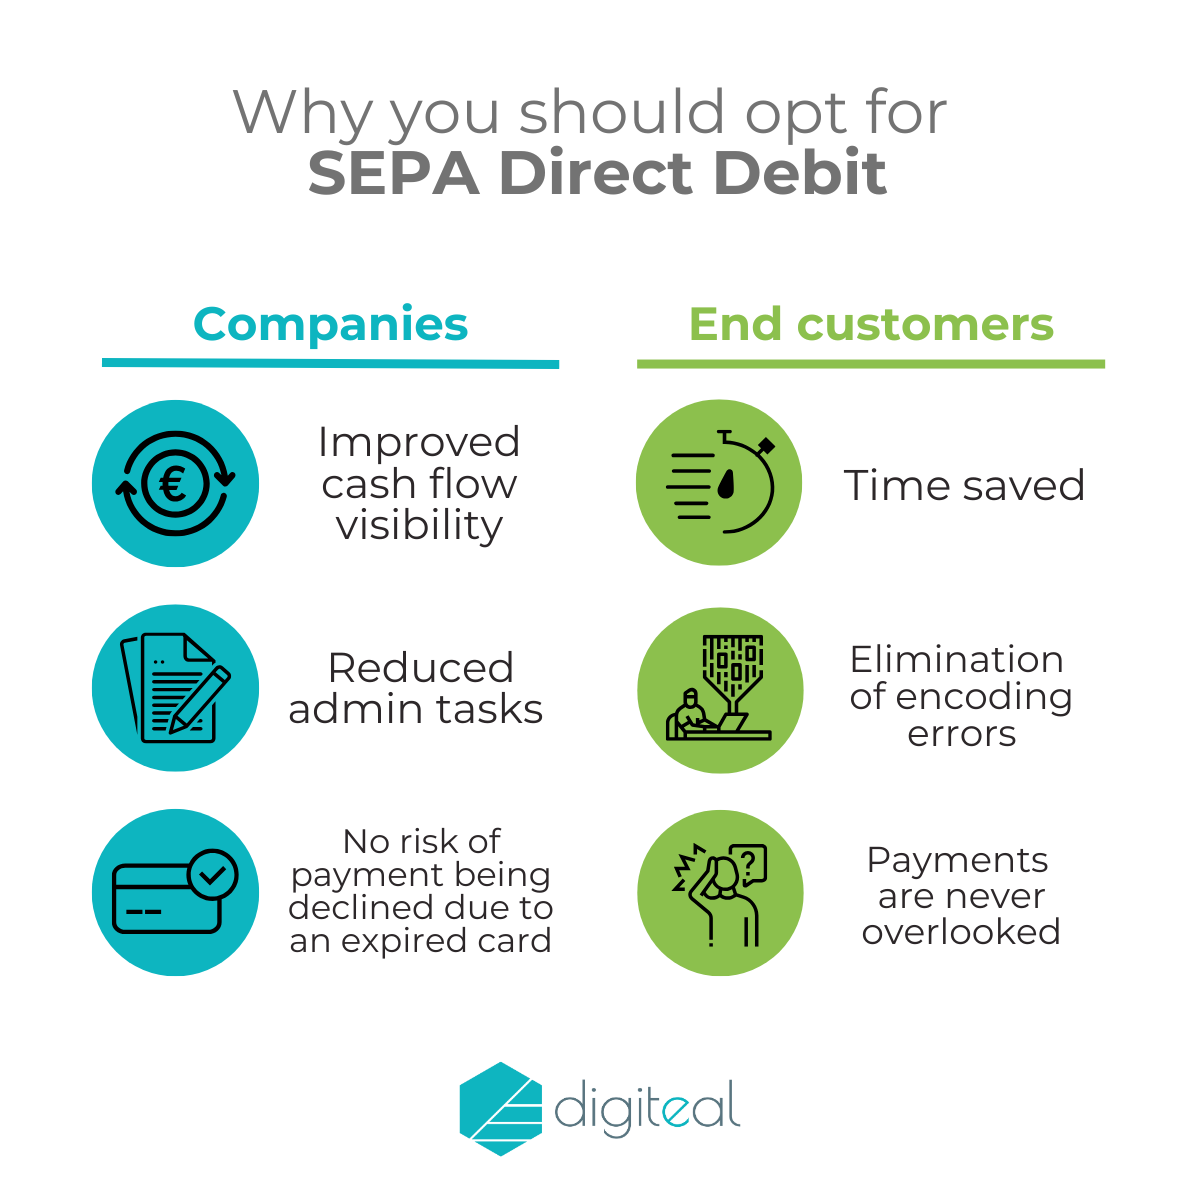
For Issuing Companies, Organizations & Administrations:

  • Gain in cash flow visibility: control over collection dates and reliable treasury forecasts
  • Efficiency gain through the reduction of administrative tasks related to payments and their tracking (no need for reminders in case of non-received payments…)
  • No risk of payment refusal due to card expiration or loss

For Clients:

  • Time-saving and peace of mind: debits are made automatically and do not require client intervention throughout the validity of the direct debit mandate
  • No risk of encoding errors related to traditional bank transfers
  • No risk of forgetting payments and, consequently, no risk of service interruption
SEPA Direct Debit: Benefits

How do SEPA Direct Debits work?

In simplified terms, it’s necessary first to ensure that both banks can process SDD debits. Then, the creditor has the debtor sign a valid SEPA direct debit mandate. Once this step is completed, the creditor sends a pre-notification before any first debit with a 14-day notice period. After that, the debit can occur automatically. Finally, the creditor must keep (or have kept by a third party) all the mandates in place to ensure their proper management until expiry.

In which cases to offer SEPA Direct Debits?

Every business that is requesting recurring payments are usually the best case for SDD. Especially if the payment collection is done every month, weeks, etc. Most common business are the Telecom, the Utilities (energy, water, etc), the companies offering online payment services.

Are SEPA Direct Debits safe?

SEPA direct debits are certainly the safest way to be paid on time and regularly. However, it is necessary to ensure that the SEPA mandate authorizing the debits is valid and confirmed. If the debtor disputes a Core debit during the first 8 weeks, the debit will be canceled by the bank, no questions asked. He can also do so within 13 months, but only if the operation was erroneous or not authorized.

Payment

Required information in SEPA Direct Debits

Each SEPA direct debit must at least include the following information:

The unique mandate reference (RUM) to identify each debit & the payment status:

  • OneOff for a one-off debit
  • First if it’s the first debit in a series
  • Recurrent for consecutive operations in a series
  • Final to indicate the last debit in a series

The mandate signing date.

How to offer and collect SEPA Direct Debits?

To set up SDD debits, you must:

  • Have a SEPA Creditor Identifier (ICS) provided by your bank
  • Establish, have signed and manage direct debit authorizations (mandates) with your debtors
  • Inform the debtor about the upcoming debit through pre-notification
  • Send the SDD debit order to the bank
  • Process the SDD debit cancellations based on the reason code
  • Keep the mandate for the duration of its validity

This process assumes possessing sufficient technical and organizational expertise to establish valid and secure SEPA mandates, to archive them, to collect, record and transmit payment orders to banks.

Detailed implementation steps to follow

  • Step 1

    Request a SEPA Creditor Identifier (ICS)

    A SEPA Creditor Identifier (ICS) is assigned to you by the National Bank of the country where your bank account is located. To obtain an ICS, you must contact your bank.
  • Step 2

    Establish and provide SEPA mandates

    First, you must create a Unique Mandate Reference (RUM) for each of the clients’ mandates. This Unique Mandate Reference can have a maximum of 35 alphanumeric characters and must not contain sensitive data or information.

    Then, it’s imperative to authenticate the client to secure your operations. You must verify the identity and consent of the client at the time of creating the SEPA mandate. Most market authentication solutions rely on the consent given alone. Digiteal goes further by asking the client to verify their identity and confirm the access to the bank account using their banking app. This verification step is conducted smoothly and integrated into the purchase journey for an optimal customer experience.

  • Step 3

    Send a pre-notification and proceed with the SEPA Debit

    Once the mandate is signed, SEPA direct debits can be collected provided a pre-notification and sending the payment order to the concerned banks.

    You are legally required to inform your clients before any payment by any useful means at least 14 days before the operation.

    However, in the case of collecting regular payments of a fixed amount, a single payment notification suffices. In the case of variable or irregular amount debits, a pre-notification must be sent each time.

    – The pre-notification must contain:
    – The amount
    – The unique mandate reference (RUM)
    – The SEPA creditor identifier (ICS)

    IBAN and BIC of the debtor (optional)

  • Step 4

    Process the SDD cancellations

    When a SDD withdrawal is canceled, the bank provides a reason code. The reason codes are 4 character codes that range from a blocked or non-existing account, insufficient funds or deceased owner.

    Some errors are final (ex: incorrect IBAN) and should lead to the cancellation of the mandate and some are temporary (ex: insufficient funds) and can lead to retries. We advise to always inform the customer of the cancellation and to not retry without the prior consent of the customer as canceled withdrawals can lead to fees for the customer and for the creditor.

  • Step 5

    Keep the mandates

    You must securely keep the direct debit mandates for their entire lifetime.

Simplify and secure your SEPA Direct Debits

Processing SEPA Direct Debits with Digiteal can greatly simplify the setup and operations.

  • You remain in control of the mandate creation process: obtain and store the SEPA Direct Debit mandate within your own customer journey, then transfer the required mandate information to Digiteal for payment processing.You can strengthen account verification: Digiteal’s Verification of Payee API verifies whether the provided name matches the customer’s IBAN holder. A 0,01 € micro-payment flow may also be used as part of your own mandate creation journey.
  • Recurring collections can then be automated: once the mandate has been properly obtained and transferred, Digiteal enables you to initiate recurring SEPA Direct Debit payments through its APIs.
  • You receive payment lifecycle updates through webhooks: following the creation of a collection, Digiteal communicates payment status changes in real-time.

Other reasons you should consider Digiteal

Digiteal’s processing is particularly advantageous in the following circumstances:

  • You need to validate bank details upfront: Our Verification of Payee API checks whether the provided customer name matches the specified IBAN holder before you finalize mandate creation. This helps detect incorrect or fraudulent information early in the customer journey.
  • You organize collections for multiple organizations across the EEA: Because Digiteal can collect from any SDD-enabled bank account and transfer funds to any account in the EEA, you gain a robust solution that doesn’t rely on specific bank connections.

Digiteal provides this service at a competitive price. Contact us to get the details.

Would you like to have more information about our SDD solution?